Banner

Health Insurance

Health insurance plans are designed to cater to different needs—whether
you are looking to cover your entire family, protect against a major illness.

Individual Health Insurance Plan

Covers a single individual.

How it works: The entire sum insured (coverage amount) is dedicated to one person. If you make a claim, it doesn’t affect anyone else’s coverage. Ideal for bachelors or individuals with specific health risks.

Family Floater Health Insurance Plan

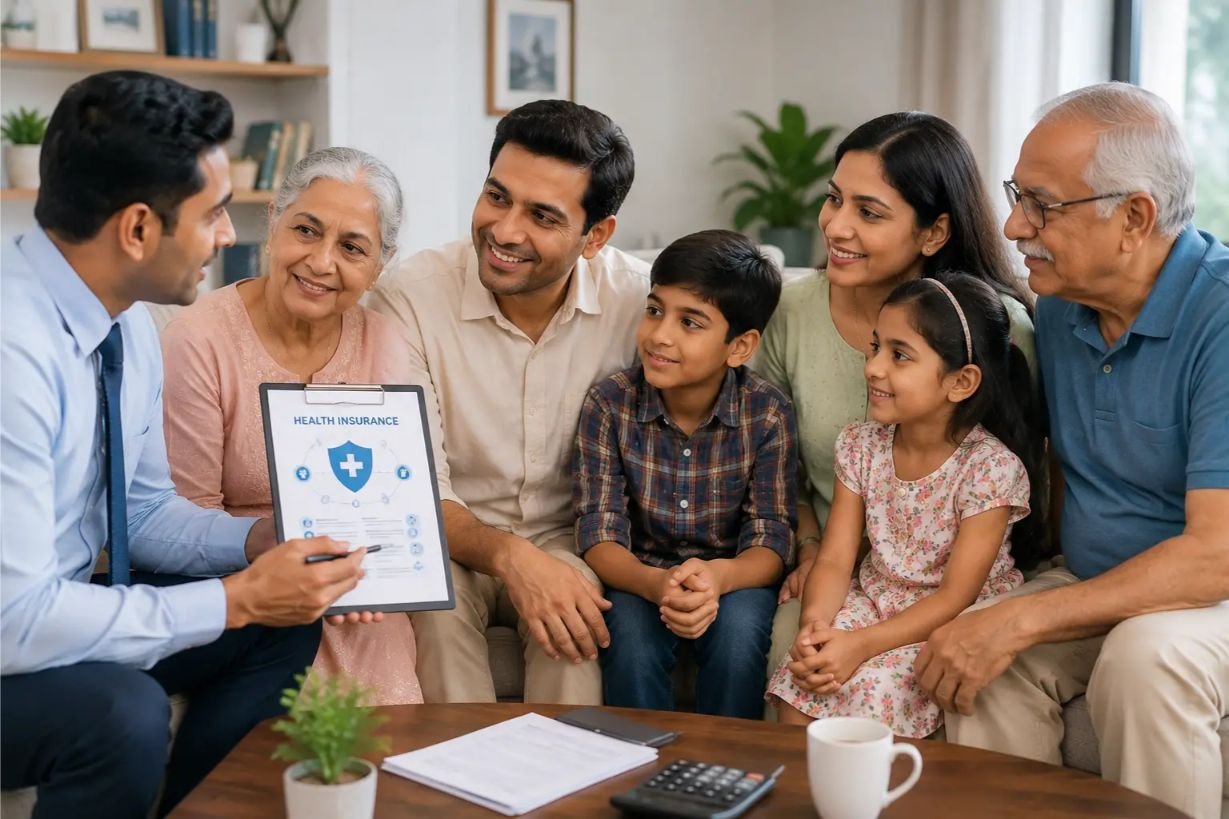
A single policy that covers your entire family (typically spouse, children, and parents).

The sum insured is shared among all family members. For example, if you have a ₹5 Lakh family floater plan, any member can use it during the year until the ₹5 Lakh limit is exhausted. It is highly cost-effective compared to buying separate policies for everyone.

Senior Citizen Health Insurance Plan

Specially designed for individuals above 60 years of age.

Since senior citizens face higher health risks, these plans offer tailored coverage for age-related illnesses, pre-existing diseases (often with shorter waiting periods), and regular health check-ups. They usually come with a co-payment clause (where the insured pays a small percentage of the claim).

Critical Illness Insurance Plan

A benefit-based policy that covers life-threatening diseases like cancer, stroke, kidney failure, or heart attack.

Unlike regular health insurance that reimburses hospital bills, a critical illness plan pays out a lump sum amount immediately upon diagnosis of a covered illness. You can use this money for advanced treatment, paying off debts, or replacing lost income.
Top-Up and Super Top-Up Health Insurance

An extension plan used to increase your existing health cover at a lower premium.

These plans activate only after a certain threshold (called a deductible) is crossed.

Top-Up: Looks at individual single claims.
Super Top-Up: Looks at the total aggregate of all hospital claims made in a single year, making it much more practical and popular.

Disease-Specific/Condition-Specific Plans

Tailored insurance for specific chronic conditions like Diabetes, Hypertension, or Cardiac issues.

Standard plans often have a 2 to 4-year waiting period for pre-existing conditions. Disease-specific plans offer coverage for these specific ailments from Day 1 or after a very short waiting period, though the premiums are generally higher.

Group Health Insurance

Offered by employers to their employees (and sometimes their dependents).

The premium is paid by the employer (fully or partially). It is highly beneficial because it usually covers pre-existing diseases from Day 1 without any waiting period, though the coverage ceases the moment you leave the company.